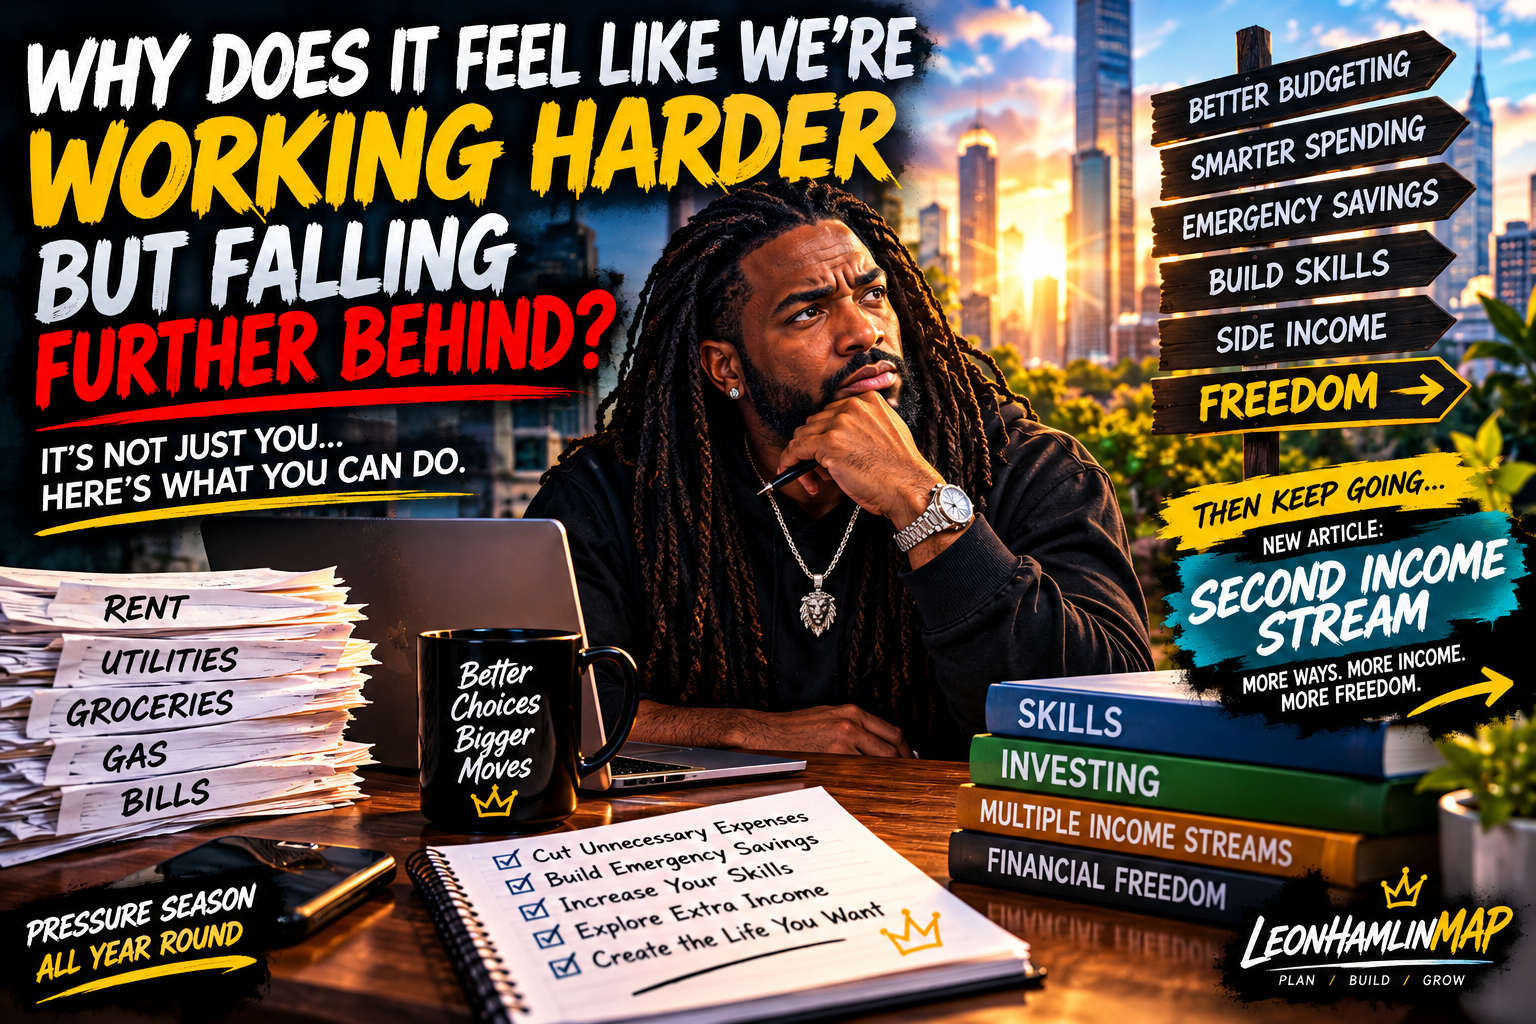
For a lot of people, working hard is still the plan—but the numbers can feel tighter than they used to. Housing, groceries, transportation, insurance, utilities, and everyday expenses all compete for the same paycheck.
That doesn’t mean the answer is panic, another get-rich-quick promise, or working every waking hour. A stronger response is to look at what you can control and build from there.
Working Harder Isn’t Always the Same as Moving Forward
More hours can bring in more money, but financial progress also depends on what happens after the paycheck arrives. Expenses, debt, savings, earning power, and unexpected costs all affect how much breathing room you actually have.
The goal isn’t simply to work harder. It’s to make the money you earn support a stronger plan.
1. Know Where Your Money Is Going
Start with the numbers you already have. Review recurring bills, subscriptions, debt payments, transportation costs, food spending, and the small purchases that are easy to overlook. You’re not looking for perfection—you’re looking for information.
Once you can see the pattern, you can decide what stays, what gets reduced, and what no longer deserves part of your paycheck.
2. Create Some Financial Breathing Room
Even a modest emergency cushion can make an unexpected expense less disruptive. If saving a large amount feels unrealistic, start with a smaller target and build the habit first. Consistency matters more than pretending you can transform your finances in one month.
3. Don’t Ignore Your Earning Power
Cutting expenses has a limit. Increasing your skills can expand the other side of the equation. That might mean training for a better-paying role, developing a freelance skill, improving your current career value, creating a product, or learning how an online business model works.
The important part is choosing something you can realistically learn and practice—not chasing every new opportunity that appears in your feed.
4. Consider an Additional Income Stream—Without the Fantasy
An additional income stream can create more options, but it should be approached like a project or business—not guaranteed money. Freelancing, services, digital products, content creation, and affiliate marketing are all possibilities, and each requires some combination of time, skill, consistency, audience, or capital.
If that’s a direction you want to explore, I put together a separate guide that breaks down a realistic way to start without pretending your first month is going to replace your paycheck.
5. Build a Plan That Can Survive Real Life
A useful financial plan has room for imperfect months. Start with a few priorities you can repeat: understand your spending, reduce unnecessary costs where practical, build savings gradually, strengthen your earning skills, and investigate additional-income opportunities carefully.
You don’t need to solve everything today. You need a direction you can keep moving in.
The Bigger Picture
Feeling financially stretched can make it seem as though the only answer is to work more. Sometimes more income really is part of the solution—but so are better information, stronger habits, useful skills, and a plan for what happens to the money once you earn it.
Review. Adjust. Save. Learn. Build. Those moves may not sound flashy, but they give you something far more useful than hype: a foundation you can keep improving.
This article is for general educational and informational purposes and is not individualized financial advice. Consider your own circumstances before making financial decisions.
Leave a Reply