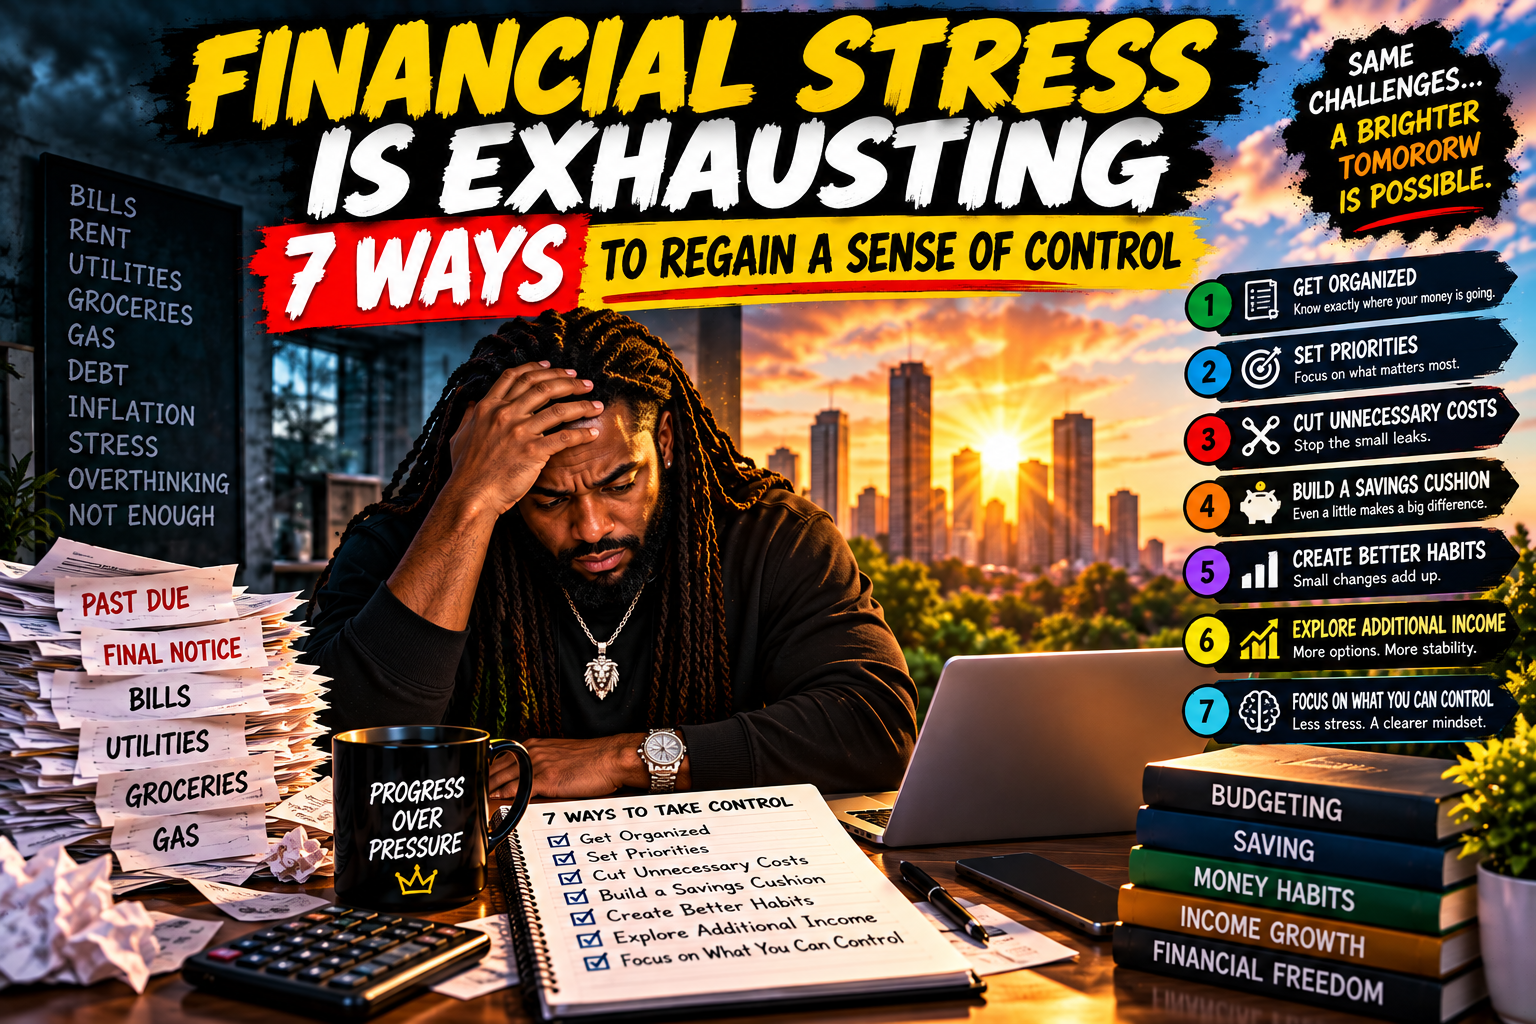
Financial stress has a way of making everything feel urgent at the same time. A bill arrives. An unexpected expense shows up. The grocery total is higher than expected. Before long, you’re thinking about five different money problems at once.
You may not be able to change every expense overnight, but you can reduce some of the uncertainty by turning a pile of worries into a short list of decisions. The goal here isn’t perfection. It’s getting enough clarity to know what your next move is.
1. Put the Numbers in One Place
When bills, balances, due dates, subscriptions, and everyday expenses are scattered across apps, emails, and paperwork, money can feel harder to manage than it actually is. Start by putting the basic numbers in one place: income, required bills, minimum debt payments, regular expenses, savings, and upcoming obligations.
You’re not judging the numbers yet. You’re simply replacing uncertainty with information.
2. Identify the Immediate Priority
Not every financial concern deserves equal attention today. Separate what is urgent from what can wait. Housing, essential utilities, food, transportation needed for work, and other critical obligations generally belong near the top of the list.
Once the immediate priorities are visible, the rest of the plan becomes easier to organize.
3. Create a Weekly Money Check-In
Instead of letting money worries interrupt you every day, choose a regular time each week to review what came in, what went out, what’s due next, and whether anything needs adjusting.
A short routine can turn money management from a constant background worry into a task with a beginning and an end.
4. Reduce Financial Decision Overload
Automating appropriate bills or savings, using a simple shopping list, setting spending limits for flexible categories, and canceling expenses you no longer value can reduce the number of money decisions competing for your attention.
The point isn’t to remove every enjoyable purchase. It’s to make your priorities easier to follow.
5. Build a Starter Cushion
A large emergency fund can take time. Don’t let the size of the long-term goal stop you from beginning. A smaller starter cushion can still help with minor surprises and begin building the habit of keeping some money between you and the next unexpected expense.
6. Separate What You Can Control From What You Can’t
You can’t personally control every price increase, interest-rate move, or economic change. You can control more immediate decisions: what you review, what you reduce, what you save, which skills you develop, and which opportunities you investigate.
If the bigger cost-of-living picture has you wondering why working hard can still feel like falling behind, I broke that question down separately here.
7. Make One Move to Strengthen Your Income
Expense management matters, but there’s a limit to how much you can cut. Improving your earning power may eventually create more room. That could mean developing a skill for your current career, pursuing a better-paying role, freelancing, creating something you can sell, or carefully exploring an additional-income model.
If building an additional income stream is one of the moves you’re considering, start with a realistic framework rather than promises of instant results.
Control Doesn’t Mean Having Everything Solved
Regaining a sense of control doesn’t mean every balance disappears or every financial problem gets solved immediately. It means you know what the numbers are, what matters first, and what you’re doing next.
Get organized. Set priorities. Build the cushion. Strengthen your earning power. Then keep moving.
Small, repeatable decisions can give you a stronger foundation than constantly searching for one dramatic fix.
This article is for general educational and informational purposes and is not individualized financial advice. Consider your own circumstances before making financial decisions.
Leave a Reply